Buy-and-Hold Real Estate Investment Strategy
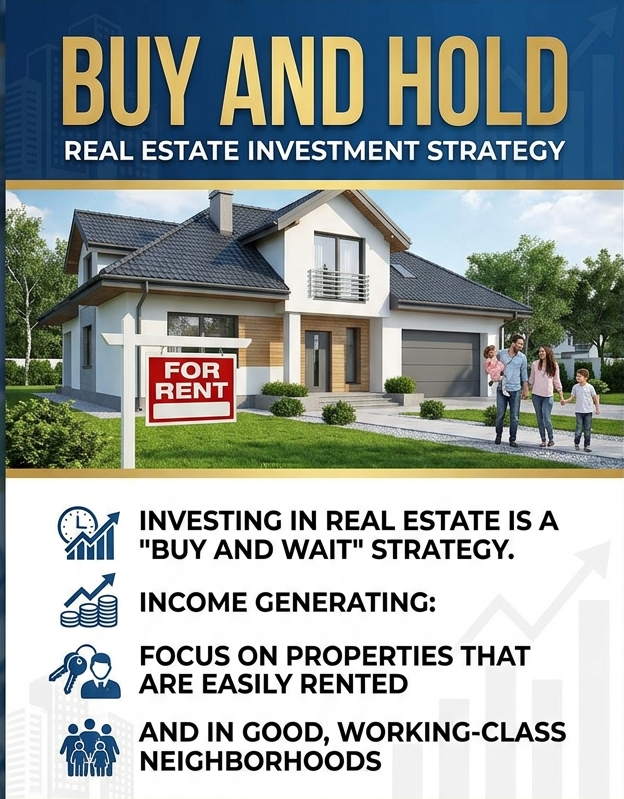
The Buy-and-Hold Real Estate Investment Strategy: The Ultimate Wealth Engine
In a world obsessed with rapid trades, quick house flips, and viral “get-rich-quick” real estate videos, the quietest strategy remains the most lethal wealth-accelerator on the planet: Buy-and-Hold Real Estate.
Flipping a house can generate a quick injection of transaction cash, but it’s essentially just a temporary job—once you stop working and selling, the income stream dries up. Plus, you get hit with massive short-term capital gains taxes.
True financial freedom, billionaire-status scaling, and the creation of an enduring family legacy don’t come from transactional velocity. They come from asset accumulation.
The buy-and-hold strategy is the disciplined practice of purchasing income-generating properties with the explicit intent of retaining them over a multi-decade horizon. Here is the mathematical breakdown of why this strategy outpaces almost every other asset class, and how to execute it like a seasoned financial strategist.
The Compounding Math Behind the Strategy
When you adopt a 10-year or 20-year buy-and-hold vision, you aren’t gambling on market timing. Instead, you are turning on a four-part compounding engine that builds wealth simultaneously:
1. The Tenant-Funded Debt Amortization
This is the ultimate wealth-building cheat code. When you utilize smart leverage to acquire a buy-and-hold property, you aren’t the one paying off the mortgage—your tenants are. Month after month, a portion of the rental income systematically reduces your principal balance. Your debt shrinks to zero over time, directly expanding your net worth without requiring you to inject another dollar of your own liquid capital.
2. Double-Compounding Appreciation
Real estate historically outpaces inflation. When you hold property long-term, your asset appreciates based on its total market value, not just your initial down payment. If you put 20% down on a $400,000 property and it appreciates by an average of 4% annually, you aren’t earning 4% on your down payment—you are earning 4% on the full $400,000. That is the exponential power of disciplined leverage.
3. Defensive, Growing Cash Flow
A well-structured buy-and-hold property generates positive cash flow on day one. But the real magic happens over time. While your major expense—your fixed-rate mortgage payment—remains completely static for 30 years, market rents naturally rise with inflation. Year after year, the margin between your rental income and your fixed expenses expands, creating an increasingly robust, defensive stream of passive liquidity.
4. Generational Tax Havens
The tax code is aggressively engineered to reward long-term property holders. Through depreciation, you can deduct a portion of the building’s structural value from your taxable income every year, allowing you to shelter your cash flow from the IRS. Furthermore, if you ever decide to transition into larger commercial or multi-family spaces, you can utilize a 1031 Exchange to defer your capital gains taxes entirely, rolling 100% of your equity into the next asset.
3 Pillars of a Disciplined Buy-and-Hold Execution
To ensure your portfolio survives market fluctuations and consistently grows, you must adhere to a strict financial roadmap:
Pillar 1: Establish Strict Capital Expense (CapEx) Reserves. Real estate is a tangible asset that requires physical upkeep. A disciplined investor never spends 100% of their net rental income. You must systemically allocate 10% to 15% of your gross rents into an untouchable reserve fund to cover future physical capital expenses (like roofs, HVAC systems, and structural maintenance) and temporary vacancies.
Pillar 2: Look for Market Fundamentals over Hype. Don’t buy properties based on emotional aesthetics or short-term trends. Look for structural fundamentals: strong employment hubs, sub-markets with excellent school districts, and areas seeing long-term infrastructure investment. These factors guarantee low vacancy rates and consistent rental demand over a 10-year horizon.
Pillar 3: Optimize Financing Structures Early. Utilize smart, modern financing vehicles to keep your capital fluid. Whether that means leveraging Bank Statement Pre-Approvals to maximize your purchasing power as an entrepreneur, or negotiating Interest Rate Buydowns paid for by seller concessions to maximize your immediate monthly cash flow, your financing should always align with your macro wealth management goals.
Archictecting Your Legacy
The real power of real estate isn’t just the physical properties we acquire today—it’s the financial literacy, stable equity, and recurring income streams we pass down to our children. Small, disciplined financial moves made right now create the massive doors your family will walk through tomorrow.
Whether you are looking to secure your very first residential rental property or scale an existing portfolio into an institutional-grade wealth vehicle, you need an advisor who understands the deep financial engineering behind asset acquisition.
Let’s connect to analyze your current position and architect a buy-and-hold strategy built for maximum long-term yield.
Click Here to Schedule Your Strategic Real Estate Investment Consultation